Moving insurance may protect household goods from certain loss or damage during a move. It does not cover every problem. The protection may come from a mover’s valuation option or a separate policy. Your move type, packing method, item value, exclusions, and claim rules all affect what you may recover.
A move can feel complete when the last box enters your new home. Then a cracked mirror, missing lamp, or damaged table can change that feeling. Learning the protection terms before moving day gives you a clear plan and fewer surprises.
Moving insurance is a common name for several kinds of protection. A mover may offer valuation coverage, while an insurance company may sell a separate policy. These choices work in different ways, so read your moving estimate and service agreement with care.
Table of Contents
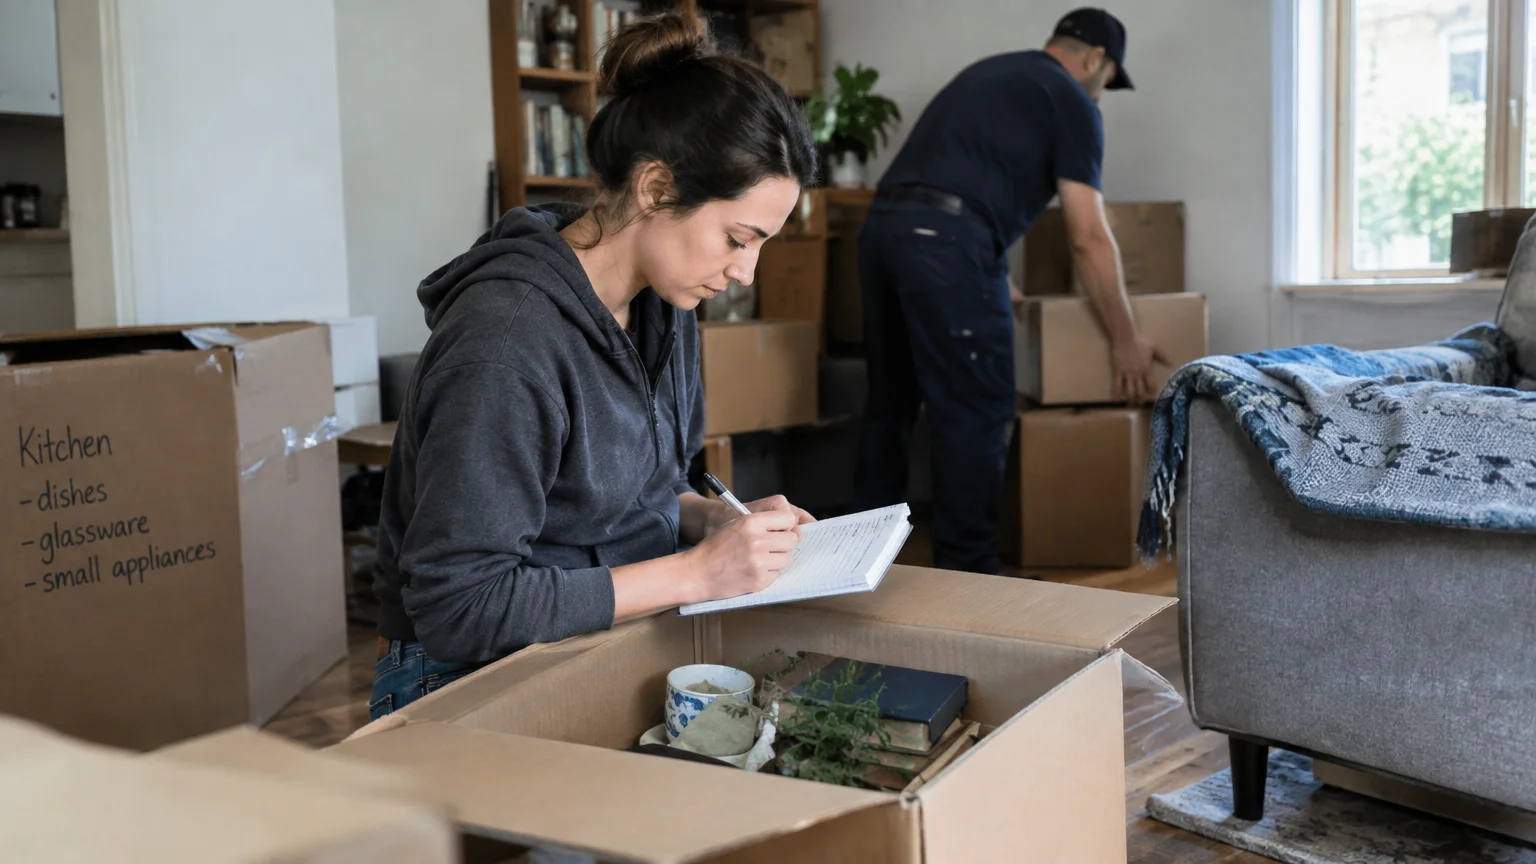
- What does moving insurance actually cover?
- What types of damage does moving insurance cover?
- What is released value protection, and how does it work?
- What is full-value protection for a household move?
- Does moving insurance cover items I pack myself?
- How do you file a moving insurance claim?
- How can you choose the right protection for your move?
- Frequently Asked Questions
- Conclusion
What does moving insurance actually cover?
Moving insurance may cover household goods that are lost or damaged during a move. The exact protection depends on the written valuation option, service agreement, and cause of the damage. Read these terms before you sign or let the crew start work.
The difference between valuation and insurance
Valuation is the mover’s stated responsibility for goods under the moving agreement. It is not always the same as an insurance policy. A separate policy may come from an insurance company and may have different limits, exclusions, claim steps, and payment rules.
People often use the words moving insurance for both choices. Ask which kind of protection applies to your move. Also ask who handles a claim and who makes the final decision. That may be the mover, an insurer, or another provider.
Your moving estimate should show the selected protection when possible. Keep a copy with the inventory, service agreement, and payment records. These papers can help if an item is damaged or missing after delivery.
Why coverage depends on the move and service agreement
Protection can change with the type of move. A local home move, long-distance move, office relocation, storage move, or loading-only job may use different terms. The agreement should say what the crew does and when responsibility starts and ends.
For example, a mover may pack, load, carry, transport, and unload your goods. Another customer may pack every box and hire loading and unloading help only. These services can affect how a claim is reviewed. Rapid City Movers can help Rapid City customers understand which questions to ask before booking.
The agreement should also list exclusions. These may include owner-packed items, existing damage, fragile goods, plants, cash, or goods that were not listed correctly. The exact rules matter more than a general promise that your belongings are protected.
What types of damage does moving insurance cover?
Moving insurance may cover accidental damage or loss that happens while the mover has responsibility for your goods. Examples include a broken table leg during handling, a crushed box during travel, or an item that never arrives. Coverage is not automatic for every type of loss.
Damage caused during packing, loading, and transport
A mover may be responsible for damage caused during services listed in the agreement. This may include packing an item, carrying it through a doorway, putting it in the truck, securing it, and unloading it at your new home.
Good records make the item’s condition easier to prove. Take clear photos of valuable goods before packing. Note old marks on the inventory. Take more photos of boxes, furniture, and appliances after delivery.
Professional movers may use blankets, wrap, cartons, straps, and other supplies. These supplies lower risk but cannot stop every problem. Report visible damage before the crew leaves when possible. Keep the damaged box or wrapping.
When loss, delay, or accidental damage may be excluded
Protection may not apply when an exclusion covers the loss. Examples include poor owner packing, normal wear, an old defect, illegal goods, or an event outside the agreement. Some plans may treat delays, storage, or weather loss in a different way.
Do not assume every problem becomes a claim. A late arrival may not have the same remedy as a broken chair. Missing parts may need a different review from a box that is completely lost.
Ask for plain answers before moving day. Ask about owner-packed goods, high-value items, electronics, artwork, jewelry, plants, food, and stored goods. Rapid City Movers can explain the service being provided and help you make a list of questions for the agreement.
What is released value protection, and how does it work?
Released value protection is a basic level of carrier responsibility chosen in the moving agreement. It often limits what the mover may owe for lost or damaged goods. The amount is not based on the item’s full replacement cost, so learn the limit before choosing it.
How basic carrier liability is calculated
With a released value option, the agreement may use a set amount tied to an item’s or shipment’s weight. Ask the mover to put the calculation in writing. Payment for a damaged television, table, or box may be much lower than its current replacement price.
The result may also depend on the item’s condition and how the damage happened. A claim reviewer may ask for the inventory, item details, weight information, photos, and proof of ownership. Do not guess the result before reading the agreement.
Released value protection may suit a move with older, low-value belongings. It may not fit a home with costly furniture, work tools, collections, or hard-to-replace items. Compare the limit with the real value of your shipment.
Why high-value belongings may need additional protection
High-value items need special care because a basic limit may not match their worth. Examples include artwork, musical instruments, antiques, computers, camera equipment, jewelry, and custom furniture. List these items and ask whether you need a separate declaration or appraisal.
A mover may also have rules for goods you transport yourself. Those items may fall outside the mover’s responsibility once they leave the truck or crew’s control. Ask before moving the item rather than after a problem occurs.
A moving company can explain its available choices, but you should read the actual terms. Rapid City Movers serves customers who want clear answers about packing, loading, transport, and protection before work begins.
What is full-value protection for a household move?
Full-value protection is a wider valuation option. It may make the mover responsible for repairing, replacing, or paying for eligible lost or damaged goods. It does not mean every item has unlimited protection. Limits, deductibles, exclusions, and declared values still apply.
Repair, replacement, or reimbursement options
When a covered item is damaged, the mover may choose to repair it. If repair is not suitable, the mover may replace it with a similar item or pay an amount allowed by the agreement. Ask how the mover chooses between these options.
Replacement does not always mean a brand-new item with every feature. A settlement may depend on the item’s age, condition, type, and availability. You may need receipts, photos, appraisals, or other proof to support a higher value.
The inventory should describe important goods clearly. “Chair” may not be enough for a custom leather chair or antique piece. Add the brand, model, material, color, condition, and visible marks when useful.
Deductibles, limits, and coverage exceptions to review
A deductible is the amount you may pay before protection applies. A policy or valuation option may also set a total limit for the shipment or certain items. These details can change the final payment, even when the mover accepts responsibility.
Read the full list of exclusions. Ask if the plan covers owner-packed boxes, goods in storage, mechanical damage, mold, insects, weather, and items moved without crew help. Also ask if high-value items must be listed separately.
The goal is not to choose the largest option without thought. Match the protection to the shipment’s value and risk. Written terms help you compare choices without relying on a quick verbal promise.
Does moving insurance cover items I pack myself?
Items packed by the customer may have different protection from items packed by the mover. Some agreements limit responsibility for owner-packed boxes because the mover cannot see how the contents were wrapped. The exact rule depends on the agreement and selected valuation option.
How self-packed boxes affect a claim
If you pack alone, use strong cartons, proper padding, and clear labels. Put heavy goods in smaller boxes. Place light items in larger cartons. Wrap plates and bowls, place them on their edge when suitable, and add padding so they cannot move freely.
Do not leave empty spaces around fragile goods. Towels, paper, and approved packing supplies can help stop movement. A photo of the open box before sealing can show how the contents were arranged.
Mark boxes with the room and a short description. You may also keep a simple list of valuable items in each carton. These steps do not change the agreement, but they can support a clearer claim review.
Items movers commonly exclude from liability
Movers may exclude or limit responsibility for certain goods. Common examples include cash, important papers, plants, food, pets, jewelry, hazardous materials, and items you move yourself. Fragile goods packed by the owner may also have special rules.
The list is not the same for every mover or service. Request the current exclusions in writing. Ask whether the crew can pack a fragile item and whether that service changes the protection terms.
For a large home or office move, professional packing can reduce handling risks. Local Movers and Commercial & Office Movers may help with furniture, equipment, files, or fragile goods. Review the agreement before work starts.
How do you file a moving insurance claim?
Report damage or loss as soon as possible. Follow the claim process in the moving agreement. Document the condition, keep damaged items and packaging, and send the requested records. Waiting can make the review harder.
What evidence should you gather before and after delivery
Before the move, photograph valuable goods from several sides. Record existing marks and keep receipts or appraisals when available. A room-by-room video can also show the condition of furniture and electronics.
After delivery, inspect boxes before throwing away packaging. Photograph crushed cartons, torn wrap, broken parts, scratches, and missing items. Check the delivery inventory against what arrived.
A useful claim file may include:
- The signed moving agreement and selected valuation option.
- The inventory, delivery papers, and written damage notes.
- Photos or video from before packing and after delivery.
- Receipts, appraisals, repair estimates, or proof of ownership.
- Messages exchanged with the mover about the missing or damaged item.
Claim deadlines, inspection steps, and settlement decisions
The agreement may set a deadline for submitting a claim. Read that deadline before the move and act soon after finding a problem. A claim may need to describe each item, explain the damage, and state the remedy you want.
The mover or insurer may ask to inspect an item. Avoid repairing, discarding, or selling damaged goods before inspection unless safety requires it. If a damaged appliance is dangerous, protect people first. Keep photos and service records.
A settlement may offer repair, replacement, or payment. Compare the offer with the agreement and ask questions when the decision is unclear. Clear records and calm communication can help keep the process organized.
How can you choose the right protection for your move?
The right protection depends on your shipment, selected services, item values, and comfort with risk. A small move with older furniture may need a different choice from a home with costly electronics or specialty goods.
Questions to ask a moving company before booking
Ask who provides the protection and whether it is valuation or a separate insurance policy. Ask what happens to owner-packed boxes, high-value goods, stored items, delays, and goods moved in a personal vehicle.
Ask how a claim starts, which deadlines apply, and whether a deductible is involved. Request the terms in writing. Then compare them with any separate policy you are considering.
Useful questions include:
- Which protection options are available for this type of move?
- What exclusions apply to items packed by the customer?
- How are high-value items listed and handled?
- Does the selected option include a deductible or total limit?
- Who reviews a claim, and what records will be needed?
- What happens if goods remain in storage after delivery?
When separate moving insurance may be worth considering
A separate policy may be worth reviewing when your shipment has valuable, fragile, unusual, or hard-to-replace items. It may also help when you want protection that differs from the mover’s valuation terms. Compare exclusions and limits, not only the policy name.
A separate policy does not replace careful packing or a written inventory. Check whether it covers the actual move, travel time, storage, and owner-packed items. The policy should explain how claims are reported and settled.
Before booking, ask Rapid City Movers about the services included in your move. Then review the written protection terms and choose an option that fits your shipment.
Key takeaways
- Moving insurance may mean valuation protection or a separate insurance policy.
- The written agreement controls limits, exclusions, deductibles, and claim steps.
- Owner-packed boxes and high-value goods may receive different treatment.
- Photos, inventories, receipts, and damaged packaging can support a claim.
- Compare protection with the real value and risk of the move.
Frequently Asked Questions
Does moving insurance cover broken furniture?
It may cover broken furniture when damage happens during a covered service and no exclusion applies. The result depends on the selected valuation option, furniture condition, and agreement. Photograph the item before and after the move, keep packaging, and report damage promptly.
Are items in storage protected after a move?
Storage protection depends on the moving agreement and selected policy. Some protection may end after delivery. Another arrangement may cover goods during a stated storage period. Ask who is responsible during storage, what exclusions apply, and whether a separate policy is needed.
Does moving insurance cover boxes packed by the owner?
Owner-packed boxes may have limited protection or may be excluded from some claims. This rule exists because the mover did not see how the contents were wrapped and placed. Ask about self-packed boxes before moving day. Keep photos of fragile items before sealing each carton.
What should a customer do when an item is missing?
Compare the delivery inventory with the items that arrived. Describe the missing item in writing, along with its last known location and identifying details. Contact the mover through the stated claim process. Keep copies of all records and messages.
Is full-value protection the same as replacement-cost coverage?
Not always. Full-value protection is a valuation option with its own rules. Replacement-cost coverage is a term that may appear in a separate policy. A mover may repair, replace, or pay for eligible items based on the agreement. Review the exact terms instead of relying on the label alone.
Conclusion
Moving insurance can help protect you from certain loss or damage, but the details matter. Valuation choices, full-value protection, owner-packed boxes, high-value goods, storage, and claim deadlines all deserve attention before the truck arrives.
A careful customer keeps records, asks direct questions, and matches protection with the shipment. Customers in Rapid City can use the same steps for local, long-distance, or office moves. Rapid City Movers helps customers plan moving services with a clear understanding of the work to be completed. Contact us to discuss the moving help and protection questions that apply to your move.